Fed Holds Rates as Microsoft, Alphabet Earnings Loom
The central bank is expected to leave its benchmark rate unchanged Wednesday as investors turn to earnings from two of technology’s biggest companies.
Market Snapshot
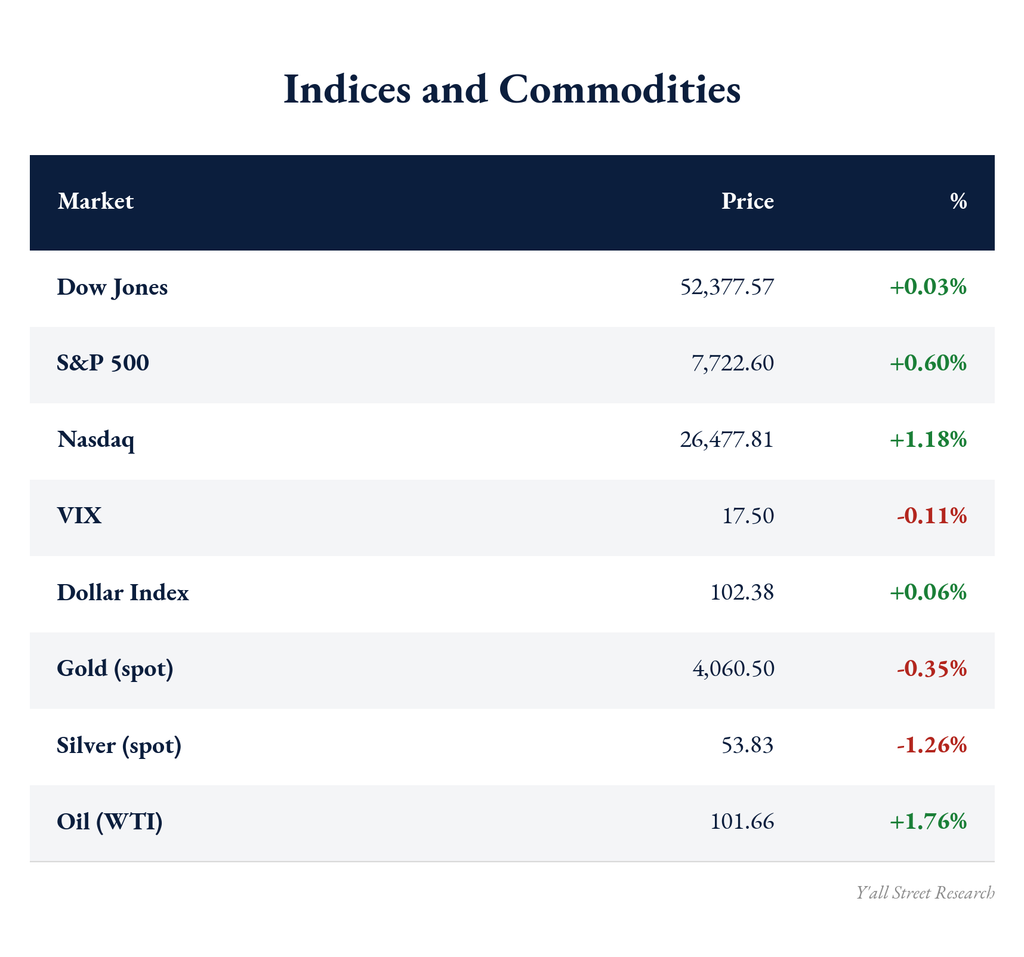
All figures are indicative opening levels as of this morning, October 28.
Stocks opened higher Wednesday, with the Dow around 52,377.57, up 0.03 percent, the S&P 500 around 7,722.60, up 0.60 percent, and the Nasdaq around 26,477.81, up 1.18 percent.
Gold eased to around $4,060.50, down 0.35 percent, and silver slipped to around $53.83, down 1.26 percent, while oil climbed to around $101.66, up 1.76 percent, on tighter supply expectations.
The VIX held near 17.50 as investors awaited this afternoon’s Federal Reserve decision and earnings from Microsoft and Alphabet after the close.
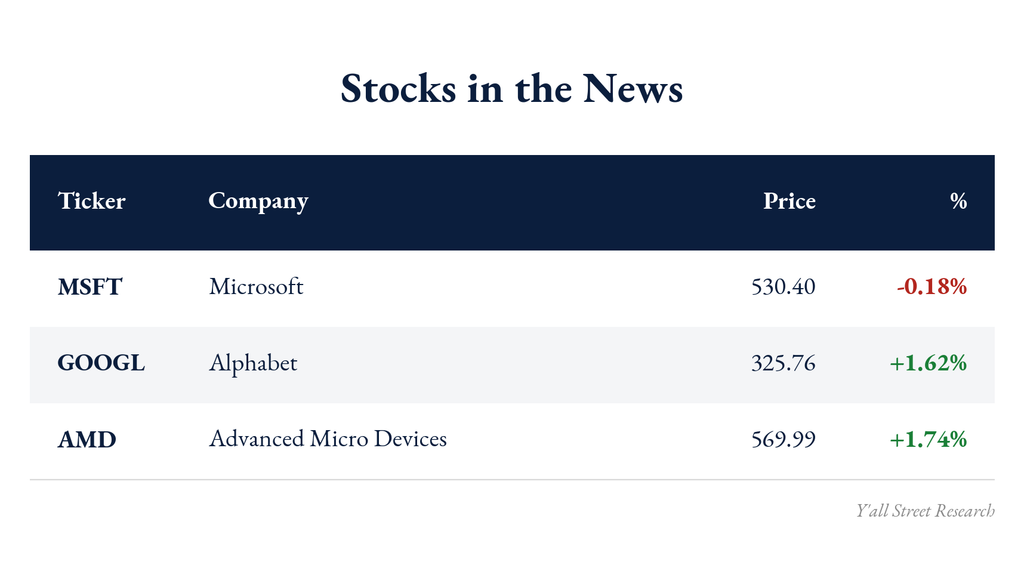
Microsoft traded around $530.40, down 0.18 percent, ahead of its fiscal first quarter results due this afternoon.
Alphabet rose to around $325.76, up 1.62 percent, extending a bounce off its October low as it also prepares to report after the close.
Advanced Micro Devices gained to around $569.99, up 1.74 percent, extending a rally tied to expanding AI chip demand ahead of its own report next week.
Main Story
The Federal Reserve is expected to hold its benchmark interest rate at 3.75 to 4.00 percent on October 28, 2026, the same day Microsoft and Alphabet both report fiscal earnings after the close.
- The Fed is widely expected to hold its benchmark rate steady at a range of 3.75 to 4.00 percent, with most economists surveyed anticipating a follow-up cut in December.
- Microsoft and Alphabet both report fiscal results after today’s close, giving investors their clearest look yet at whether heavy AI infrastructure spending is translating into revenue growth.
- Markets have largely priced in a quiet Fed decision, which means today’s earnings, not the rate announcement, are likely to set the tone for stocks into the end of the week.
Chart of the Day
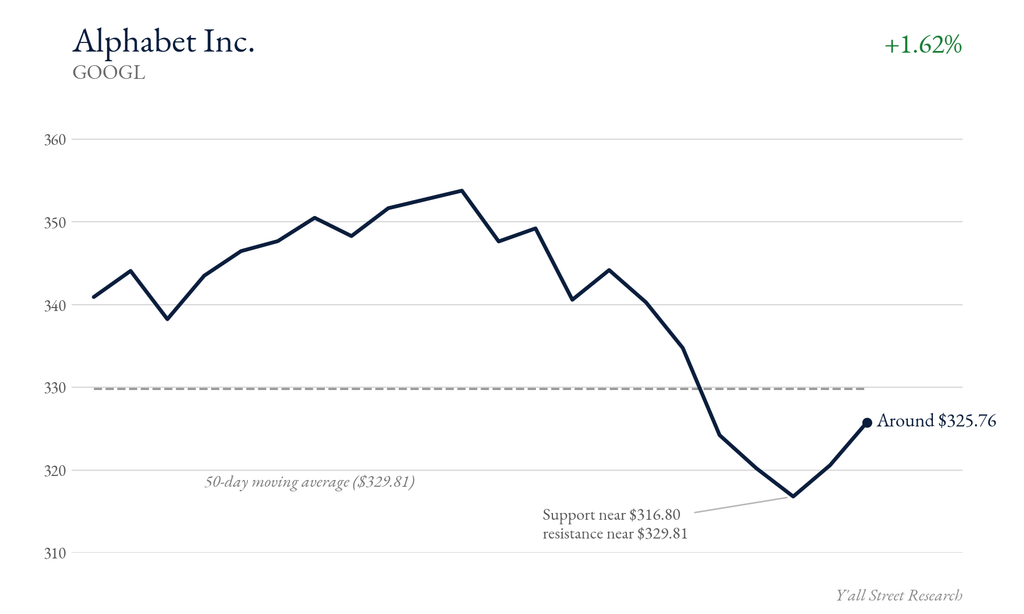
Alphabet trades around $325.76 in early action Wednesday, extending a bounce off its October low near $316.80 ahead of this afternoon’s earnings report.
The stock remains below both its 50-day average around $329.81 and its 200-day average around $342.89, with momentum readings still soft heading into the print.
Traders are watching whether a strong report can push shares back above the 50-day average or whether another miss sends the stock retesting support.
Technical Trading
GOOGL levels from Investing.com’s Wednesday technical summary.
- The 14-day RSI reads around 40.34, reflecting weak but not yet oversold momentum.
- MACD sits around negative 2.403, consistent with the stock’s recent downtrend, with shares below both the 50-day ($329.81) and 200-day ($342.89) moving averages.
- Classic pivot resistance sits around $322.06, with support near $316.80, a level that has held on each test since late October.
Global News
- The Federal Reserve opened the second day of its policy meeting, with markets pricing almost no chance of a hike at today’s decision and broad expectations for another cut before year end.
- South Korea’s SK Hynix posted a record quarterly profit on surging demand for AI memory chips, helping send the KOSPI sharply higher and lifting chipmakers across Asia overnight.
- Qatar hosted a new round of talks aimed at easing regional tensions tied to Iran, adding to a string of Middle East diplomatic moves this week.
- The Trump administration moved to roll back a Biden-era rule requiring oil and gas companies to curb methane emissions from wells and pipelines.
Texas News
A tanker carrying the first shipment of Venezuelan crude under a new US access agreement arrived at Corpus Christi this week, delivering roughly 1 million barrels bound for Exxon Mobil and Citgo refineries.
The arrival coincided with President Trump’s campaign stops in Corpus Christi and Lubbock ahead of the state’s midterm elections.
Looking Ahead
Wednesday, October 28: The Federal Reserve announces its rate decision this afternoon, followed by earnings from Microsoft and Alphabet after the close, in what could be the most consequential day of this earnings season.
Thursday, October 29: Meta’s stock offering is expected to price, the next test of investor appetite for the AI infrastructure buildout once Wednesday’s results are in.
The Y’all Street Podcast
Evan talks with Wasif Latif, Co-Founder and CIO of Sarmaya Partners, about his “Return to Tangibles” thesis: markets shifting from tech and long-duration financial assets toward energy, metals, commodities, and infrastructure. They cover what’s changed since the 2008 financial crisis, and frame AI as much a physical infrastructure story (power, natural gas, copper, uranium) as a software one. Latif ties it back to how he’s positioning around that view through Sarmaya’s LENS ETF.
Prices from Yahoo Finance, CNBC and Fortune. Technical levels from Investing.com and FXStreet. News from Reuters, Al Jazeera and CNBC.
For informational purposes only. Not investment advice. Prices are indicative opening levels and may differ from your broker.